The essentials in one coffee
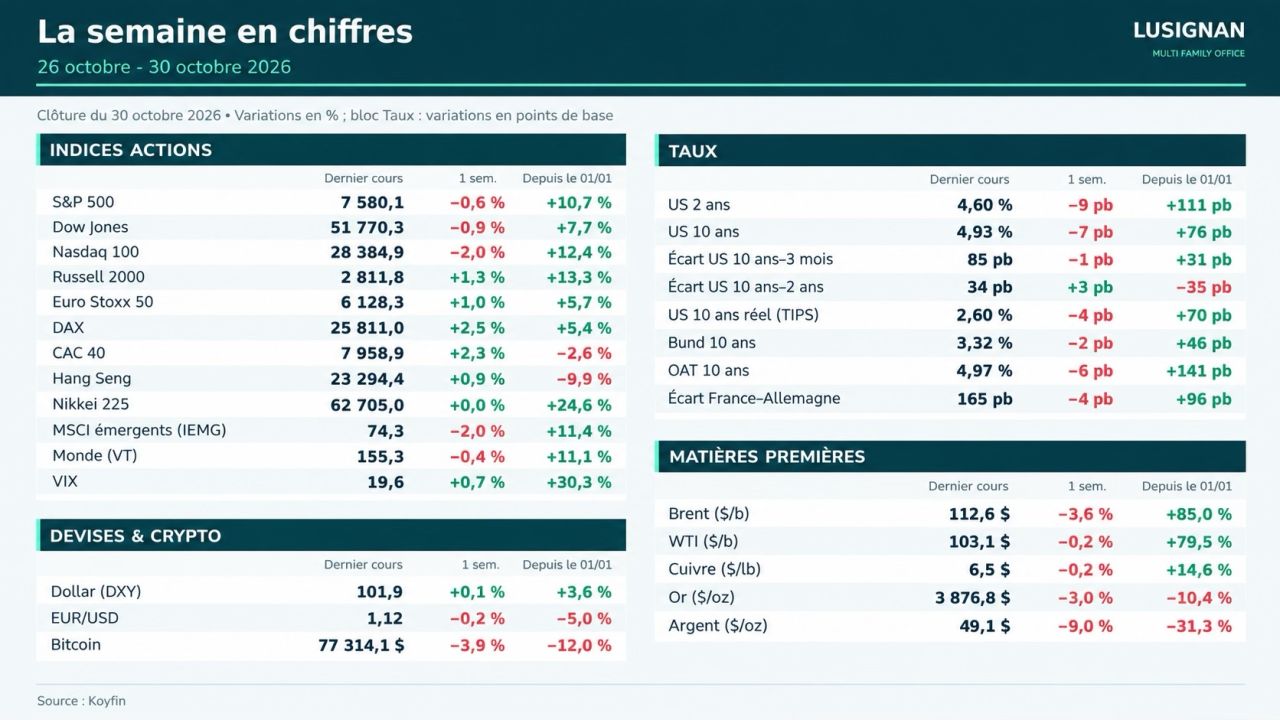
- AI & earnings: Alphabet −12.6% on Thursday, Intel −28.6% on Friday; the Nasdaq 100 ends in correction territory, more than 10% below its 6 October record.
- Rotation: the CAC 40 gains 2.4% and Goldman Sachs's ex-AI S&P 500 basket is heading for its best month in nearly three years.
- Rates: the US 10-year loses nearly 40 bp in October, to 4.93%; the Fed, ECB and Bank of Japan remain on hold.
- France: Moody’s maintains the Aa3 rating (negative outlook); solemn vote on the revenue side of the 2027 budget on Tuesday 3 November.
EQUITIES & AI
Earnings: growth is no longer enough, the market demands cash
- Alphabet: revenue of $127.6bn (+25%) and Google Cloud +103%, but disappointing advertising and free cash flow of −$9.1bn; the stock loses 12.6%, its worst session in more than twenty years.
- Microsoft convinces: Azure +48% and free cash flow of $18.6bn, $10bn more than anticipated; Intel (−28.6%) and ServiceNow (−34% over the week) are punished.
- The real issue, cash: analysts now anticipate cash burn of around $86bn over twelve months for the five large hyperscalers (Bloomberg), against more than $700bn of investment planned in 2026 at the four American giants.
LUSIGNAN'S VIEW — No bubble bursting: it is the valuation of the biggest spenders that is readjusting. An environment that favours active, disciplined management, attentive to valuations, cash flows and return on investment.
CREDIT
Financing AI: credit sorts between issuers
- Risk premiums up over three months: 87 bp for IG (+12), 338 bp for HY (+72), 1,111 bp for CCCs (+188); HY bonds financing data centres lost 6.7% between the end of June and mid-October.
- An open but selective market: record global bond issuance of $6,610bn; Microsoft raises $25bn with $115bn of demand, Meta lifts its raise to $97.5bn.
- No generalised crisis: the HY default rate is 3.4%, real but contained stress.
LUSIGNAN'S VIEW — This sorting by credit quality is healthy: favour solid issuers and keep a close eye on new issues, non-AI spreads and cash flow after investment.
RATES & CENTRAL BANKS
The easing is here, central banks remain cautious
- Safe-haven bonds: the US 10-year ends October at 4.93%, after exceeding 5.3% in early October; bond index funds have attracted around $58bn since the start of October.
- Fed: rates held between 3.75% and 4.00% (10 votes to 2); futures give around an 84% chance of a hike in December.
- ECB and Japan: deposit rate held at 2.5%, door open for December; Christine Lagarde will leave the presidency in February. The Bank of Japan paves the way for a hike by the end of the year.
LUSIGNAN'S VIEW — Bonds are once again a hedge for the equity portfolio and current yield levels constitute an entry point. A protection that nevertheless remains fragile as long as oil keeps inflationary pressures alive.
FRANCE
Moody’s buys time, the budget still has to be passed
- Rating maintained: Aa3 with a negative outlook, conditional on the adoption of the 2027 budget; the 10-year OAT has moved back below 5%.
- OAT-Bund spread: narrowing from 167 to around 155 bp on Thursday, before rising back towards 165 bp on Friday.
- Economy: Q3 GDP down 0.1% (Insee); next steps on 3 November (vote on revenue), the 17th (overall vote) and the 27th (S&P review).
LUSIGNAN'S VIEW — Political risk remains intact. Current spread levels can constitute an entry zone for an investor who accepts volatility; internationally oriented groups remain less exposed than domestic stocks.
ENERGY & GEOPOLITICS
Oil: flows are back, prices are not
- Brent: the December contract expired at $117.64; +13.6% in October, the fourth consecutive monthly rise.
- Supply under strain: global inventories fell by 509 million barrels between the end of February and the end of September (IEA); strike claimed by the Houthis on Saudi Arabia's largest refinery.
- The majors benefit: TotalEnergies posts a record adjusted net income of $9.1bn.
LUSIGNAN'S VIEW — A barrel durably above $110 remains the main threat to rates. To watch: global inventories, the spread between Brent maturities and shipping costs.
OTHER NEWS
In brief
- Brazil: surprise re-election of Lula (51.8%); the Ibovespa falls by as much as 17% and the real by as much as 11% against the dollar on 26 October.
- Midterms, Tuesday 3 November: Polymarket gives the Democrats a 91% chance in the House and 66% in the Senate; a scenario deemed already priced in (Bloomberg).
- Gold & crypto: gold falls back below $4,000 ($3,875, −3.1% over the week); Binance suffers a $6.3bn hack, bitcoin loses 5%.
This is not investment advice.