The essentials in one coffee
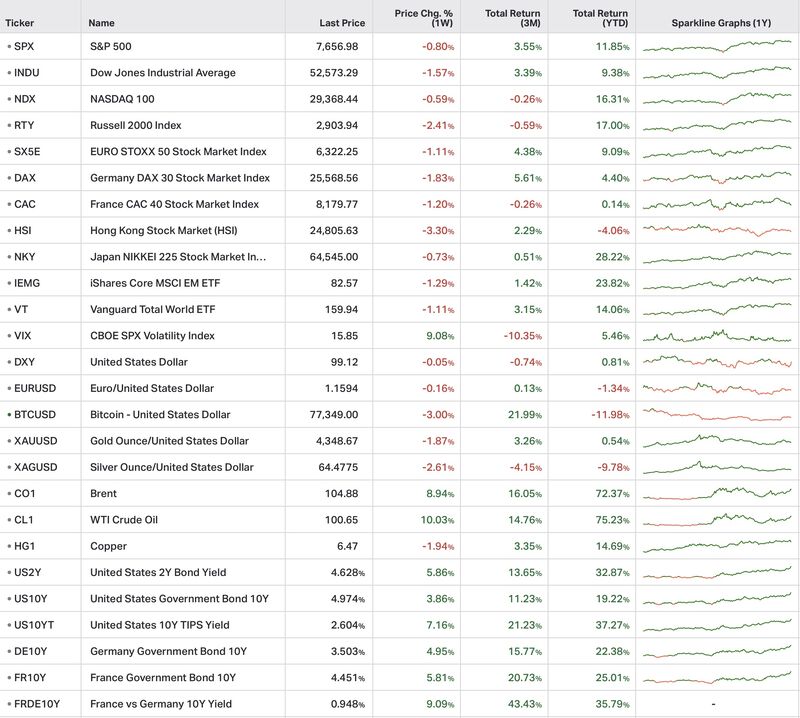
- Central banks: the ECB raised its deposit rate by 25 bp to 2.50% on Thursday (unanimous decision); the Fed must decide on 16 September, with a hike seen as roughly 85% likely.
- US inflation: August CPI comes in at 3.4% year on year (+0.4% on the month), core at 2.4% (+0.3% on the month, above consensus); PPI exceeds 5% year on year.
- Energy: Brent climbs 8.9% to $104.9 (peak at $120 on Friday morning); US diesel crosses $6 a gallon for the first time.
- France: the OAT-Bund spread ends at 95 basis points, highest since 2012; the government abandons the deficit target of 5% of GDP.
CENTRAL BANKS
The ECB hikes, the Fed must decide on 16 September
- ECB, Thursday 10 September: deposit rate raised from 2.25% to 2.50%, unanimous decision; Christine Lagarde described the decision as “obvious” and expects inflation above target until the first half of 2027.
- US CPI (Friday): core comes in at +0.3% on the month against +0.2% expected (2.4% year on year); the probability of a Fed hike on 16 September rose from 60% to 85% in a week.
- Euro curve: the 10-year CMS ends at 3.54% and the 30-year at 3.48%, an inversion of 6 basis points between the two; the 10-year Bund set its highest since 2009.
LUSIGNAN'S VIEW — The adjustments under way look like a response to the energy shock rather than a new tightening cycle; at these levels, rates continue to offer favourable conditions for capital-protected solutions and quality carry.
ENERGY & GEOPOLITICS
Brent above $100: diesel crosses $6, freight at a record
- Crude: Brent rises 8.9% over the week to $104.9, with a peak at $120 on Friday morning; European gas (TTF) climbs 10.5% to €79.52, up 193% over the year.
- Refined products: US diesel exceeds $6.05 a gallon as a national average, an all-time record; supertanker freight Middle East–China reaches nearly $800,000 a day, also a record.
- Crypto-assets and commodities: in a week unfavourable to risk assets, bitcoin falls 3.0%, gold 1.8% and copper 1.9%.
LUSIGNAN'S VIEW — Goldman Sachs recommends hedging geopolitical risk through gas and refined products rather than crude, as supply shocks are more pronounced there; as long as shipping and refining remain under strain, diversification and hedging remain appropriate.
DEBT & BUDGETS
France: the risk premium at its highest since 2012
- OAT-Bund spread: it ends the week at 95 basis points, the highest since the 2012 sovereign debt crisis; 5-year CDS widened for nine consecutive sessions up to Thursday.
- Budget: Roland Lescure abandoned on Friday the deficit target of 5% of GDP (“more than 5%”), and the 2026 growth forecast is cut to 0.5%.
- Equities: the CAC 40 erased on Thursday all of its gains for 2026, underperforming the Euro Stoxx 50 (–1.1% over the week) and the DAX.
LUSIGNAN'S VIEW — The widening of the OAT-Bund spread is becoming a lasting component of French financing costs rather than a one-off episode; without calling into question the State's credit quality, it offers more attractive returns on OATs for savers who gain exposure through protected solutions.
OTHER NEWS
In brief
- Results: Oracle posts revenue up 30% to $19.3bn, driven by cloud (infrastructure +121% year on year) and an order backlog of $664bn (+46%); its $20bn share issuance programme is completed.
- Novartis: three clinical setbacks in the week — failure of pelacarsen, failure of del-desiran, halt of a cell therapy after three deaths; the stock lost up to 10% in Zurich.
- China: exports rise 25% in August, supported by AI; the trade surplus reaches $119bn.
This is not investment advice.