The essentials in one coffee
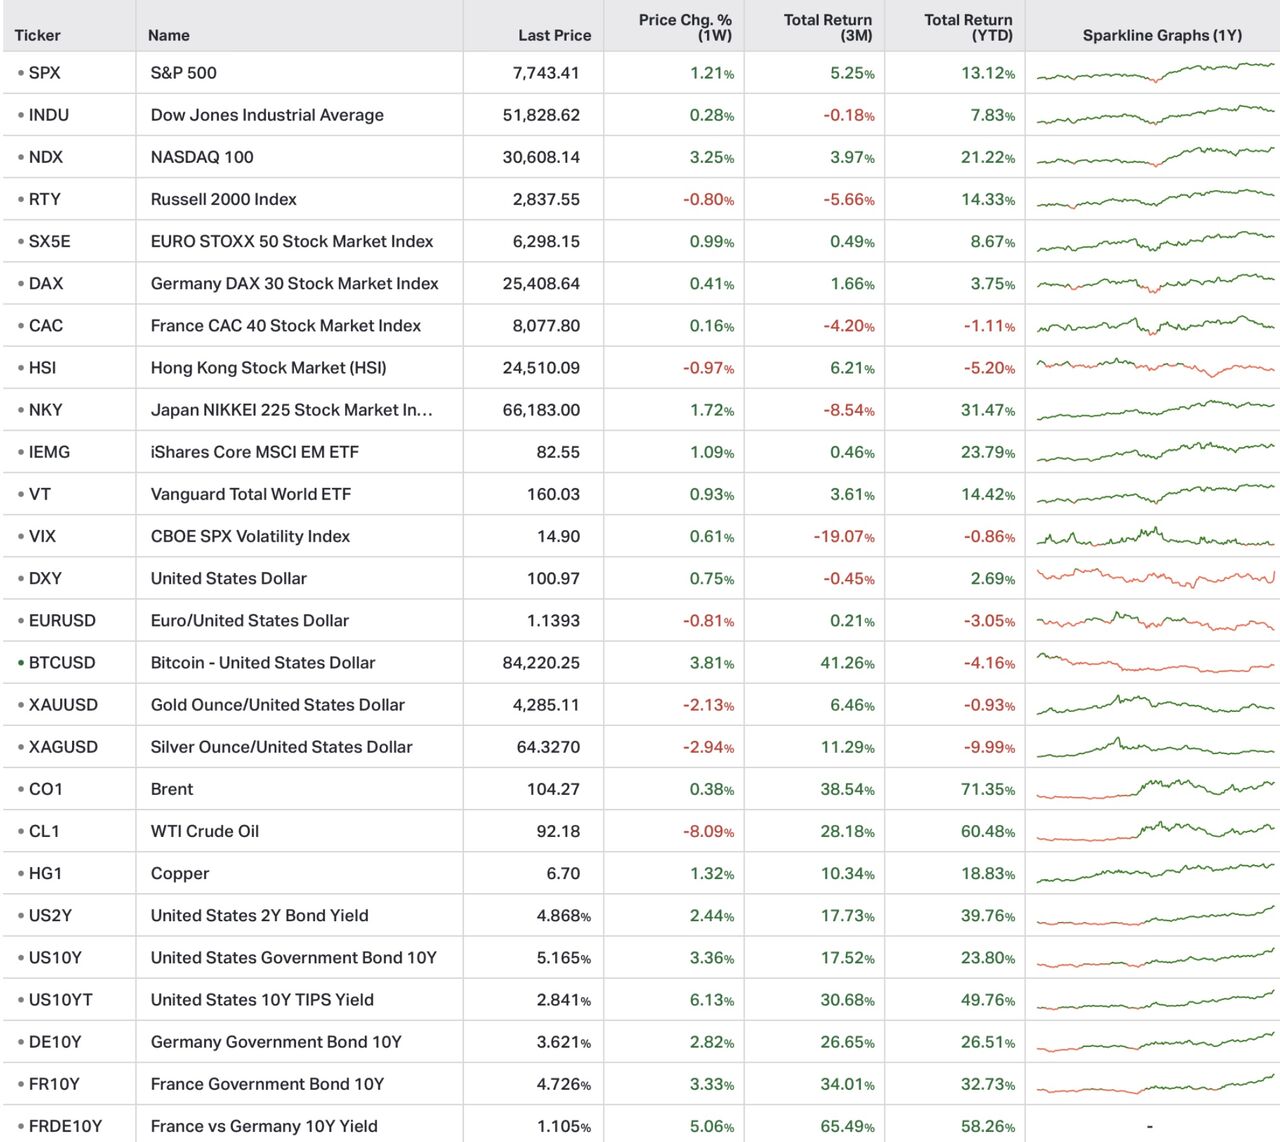
- Long rates: the US 10-year touches 5.21% on Thursday, highest since 2007; the 30-year reaches 5.53%, after disappointing auctions.
- Iran: verbal escalation between Washington and Tehran; Brent exceeds $106 on Thursday and ends at $104.3.
- France: no improvement, the OAT-Bund spread ends at 109 bp and the 10-year OAT touched 4.72%, highest since 2008.
- Equities & AI: Nasdaq 100 at a record on Tuesday; Meta +11.4% on Monday lifted by Muse, AMD crosses $1,000bn in market capitalisation.
RATES & CENTRAL BANKS
The bond sell-off has arrived, and it is worldwide
- Demand falters: the 5-year is awarded at 5.033% with the second-largest “tail” in history (3.1 bp), the 7-year at 5.085%, a record since 2009; the Treasury buys back only $4.08bn of the $6bn targeted.
- A global move: average yield on global sovereign debt close to 4%, unseen since 2007; 10-year JGB at 3.08%, highest since 1996; 10-year Bund at 3.60%.
- Fed under pressure: US composite PMI at 58.4 and household inflation expectations at 4.6%; swaps price three 25 bp hikes over twelve months, Morgan Stanley expects only two.
LUSIGNAN'S VIEW — No crisis of Fed credibility, but a stronger demand for compensation. Threshold to watch: 5.25% on the US 10-year, beyond which bonds stop hedging equities. At these levels, long rates make it possible to lock in yield over the long term.
ENERGY & GEOPOLITICS
Iran and Hormuz: the physical side loosens up, the political side hardens
- Flows resume: crude and LNG through Hormuz at a six-month high according to CENTCOM; Saudi exports through the strait at 2.9 mb/d, against 0.7 mb/d in August (JPMorgan).
- Verbal escalation: Donald Trump threatens at the UN to “annihilate” Iran; Tehran threatens to extend the front to the Indian Ocean. Brent, back below $100 early in the week, climbs above $106 on Thursday.
- Diesel under strain: $6.51 a gallon in the United States, a record, up 73% since the start of the war; in Europe, the diesel premium over Brent exceeds $95 a barrel.
LUSIGNAN'S VIEW — Energy remains the first channel through which this conflict feeds inflation, hence central banks, hence long rates. Only a lasting resumption of flows through Hormuz will ease prices: do not overreact to positive headlines without real progress.
DEBT & BUDGETS
France: no improvement, distrust sets in
- The spread: 109 bp on Friday after a peak at 111 bp on Thursday, against 82 bp at the start of the year; the 10-year OAT closes at 4.69%.
- The fundamentals: downgrade by Scope; deficit expected at 5.4% of GDP this year and debt forecast at 121.7% of GDP in 2027, despite the €54bn effort proposed by Sébastien Lecornu.
- The Banque de France raises its voice: Emmanuel Moulin considers a 100 bp spread “far too high” and recalls that the ECB's anti-fragmentation instrument would only come into play if measures are taken at national level.
LUSIGNAN'S VIEW — No disorder yet, but a price: that of a political risk the market no longer thinks it can pass on to the ECB. Vigilance during the October-November budget review, which will be decisive.
EQUITIES & AI
The Nasdaq at a record, the AI bill grows
- A concentrated rally: Nasdaq 100 +3.3% and S&P 500 +1.2% over the week, but Russell 2000 −0.8% and CAC 40 +0.2%; only 19% of US stocks beat their index over one month.
- A zero risk premium: the forward earnings yield of the S&P 500 has fallen to the level of the 10-year, a first since early 2025.
- The bill: capex of the five hyperscalers expected at $800bn to $1,200bn in 2027 (Goldman Sachs), $2,800bn of off-balance-sheet commitments linked to AI (Moody's); Oracle invokes force majeure on its Jupiter data centre, without cancellation.
LUSIGNAN'S VIEW — Valuations have already calmed down (22 times earnings for the median AI infrastructure name, against 32 in April); the risk has shifted from multiples to debt, and a rate-hiking cycle is precisely when it gets tested. Selectivity.
OTHER NEWS
In brief
- Washington-Beijing: trade truce extended to 10 January, during Xi Jinping's first state visit to Washington in eleven years.
- Gold: −2.1% to $4,285, negative since January, but the metal is compressing into a triangle; the $4,000 support remains the line to watch.
- Coming up: August PCE with its change of methodology on Wednesday 30, US employment for September on Friday 2 October.
This is not investment advice.