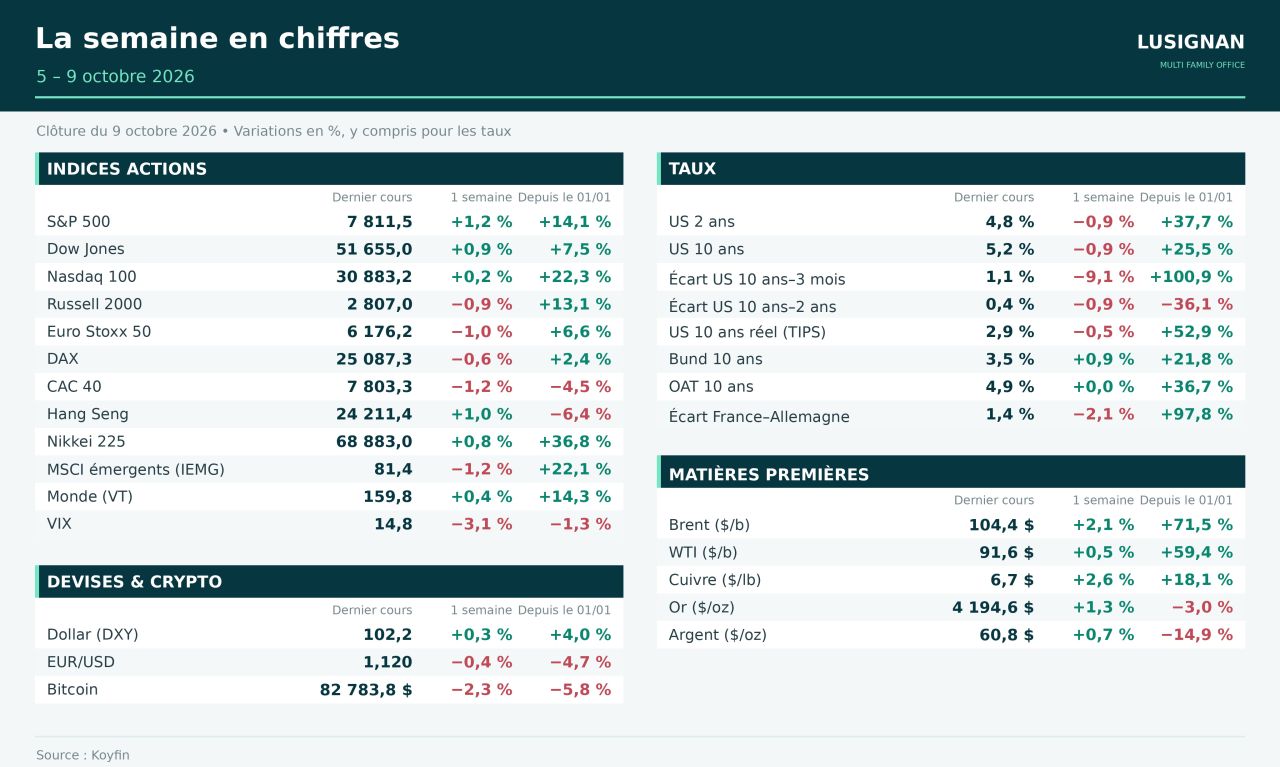
The essentials in one coffee
- Rates: disappointing US jobs data, a Fed hike on 28 October all but ruled out; December under consideration.
- Euro area: inflation at 3.8%, driven by energy; euro at its lowest since May 2025, 29 October ECB meeting open.
- Energy: Strait of Hormuz still closed; the G7 releases 100 million barrels, Brent ends the week at $104.
- France: 2027 budget with €54bn of effort; the OAT-Bund spread falls back to 137 bp after its highest since 2011.
FRANCE · DEBT & BUDGET
OAT-Bund spread: France catches its breath
- 2027 budget (1 October): €54bn of effort, including €43bn of new measures, for a deficit targeted at 5% of GDP after 5.4% in 2026; a target deemed "a minimum" by the HCFP.
- RN counter-budget (6 October): deficit at 3.7% of GDP as early as 2027 and 2.2% in 2032; the spread touched 127 bp that day and ended the week at 137 bp, 10-year OAT at 4.85%.
- ECB and investors: Christine Lagarde reiterated that the ECB "has the instruments" to address disorderly moves; Amundi has resumed buying OATs at 150 bp, "without excess".
LUSIGNAN'S VIEW — The OAT pays for a real risk, now bounded by a timetable and targets; volatility should persist until the presidential election: active, diversified bond management focused on quality.
RATES & CENTRAL BANKS
US jobs stall, European inflation at 3.8%
- Fed: 29,000 jobs created in September against 85,000 expected, unemployment at 4.2%; the market now prices only around a 19% chance of a hike on 28 October, 85% in December.
- Treasuries: auctions found buyers at yields unseen in twenty years; the 10-year ended at 5.24% after approaching 5.35%, a rise in real rates more than an inflation scare.
- Euro area: inflation at 3.8% in September (energy +18.8%), 3.4% in France; deposit rate at 2.50%, euro down to $1.1161, its lowest since May 2025.
LUSIGNAN'S VIEW — Yields rarely seen in twenty years offer protected savings an attractive return; US inflation on 14 October will tell whether the return of long-term buyers is confirmed.
ENERGY & GEOPOLITICS
Hormuz closed: the G7 buys time, freight soars
- G7 (2 October): 100 million barrels of reserves over four months, diesel first, part of which consists of unexecuted commitments from the March programme; European diesel temporarily fell by more than 8%.
- Brent at $104 (+2%): ninth attack on a tanker in the area since the start of October; Donald Trump states that the United States will not attack Iran before 3 November. Hurricane Isaias has already shut in 1.3 million barrels per day in the Gulf of Mexico.
- Logistics and gas: chartering a US–Asia supertanker costs $77 million, around $38.50 per barrel; European gas (TTF) gains 7.2% to €80.18.
LUSIGNAN'S VIEW — The risk of escalation has receded in the short term, but not the cost of energy for Europe: reserves provide relief without resolving anything. To watch: diesel actually delivered around 22 October.
EQUITIES & EMERGING MARKETS
Wall Street near records, Europe lags, Brazil soars
- Two speeds: the S&P 500 gains 1.2% to 7,812 points (+14% since January) while the CAC 40 falls 1.2% (−4% since January) and enters correction territory, weighed down by banks, telecoms and Schneider Electric.
- AI: a scare on Thursday over OpenAI's annualised revenue (around $50bn presented, against nearly $70bn assumed by the market): Nasdaq 100 −1.4%, semiconductors −3.4%; Nvidia came close to a $6,000bn market capitalisation.
- Brazil: Flávio Bolsonaro leads Lula in the first round (47.03% against 45.16%); the Ibovespa gains 8.8% to a record, the real 4.4%. Second round on 25 October.
LUSIGNAN'S VIEW — A narrow rally and record dispersion: selectivity, and diversification beyond the AI champions alone. In Brazil, prices anticipate reforms that have yet to materialise.
OTHER NEWS
In brief
- Schneider Electric: acquisition of US software publisher PTC for $22.6bn (42% premium), its largest acquisition; the stock lost 10% on Monday.
- Telecoms: SpaceX buys spectrum in the United States to become a mobile operator; Verizon posts its worst session since 2002, Deutsche Telekom loses 7.9%.
- Life insurance: net inflows of €43.5bn over eight months and record assets of €2,171bn, driven by unit-linked contracts (€33.9bn).
This is not investment advice.