The essentials in one coffee
- United States: Democrats retake Congress — 54 seats to 44 in the Senate, 254 to 162 in the House (AP, 8 November); a presidential veto stands in the way from January.
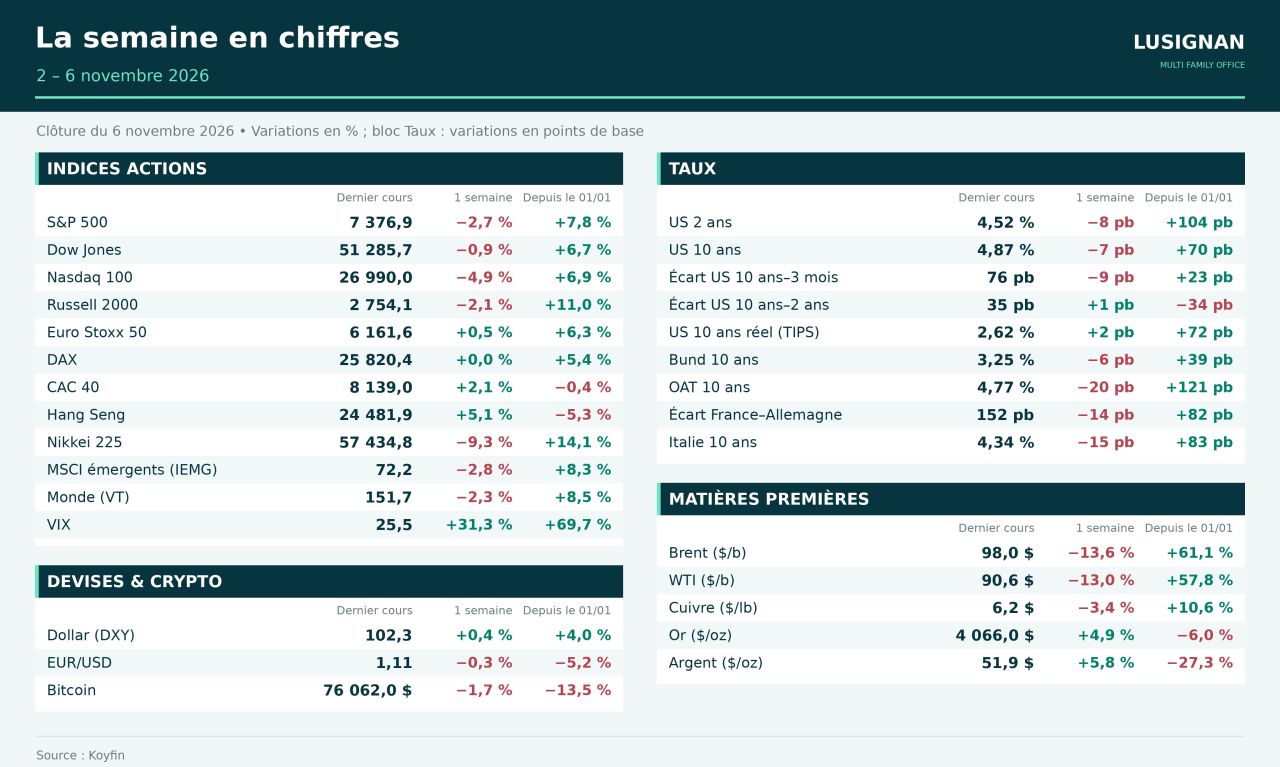
- Technology: Nasdaq −5.5% and semiconductors −12% on 5 November on fears of a brake on data centres; partial rebound since.
- Rates: US payrolls +165,000, euro area inflation at 4.0%, Bank of England at 4.00%, French budget rejected.
- Energy: Brent at $98, −16% over the week on hopes of a deal with Iran; gas towards €85/MWh.
UNITED STATES
Congress flips, the president keeps his veto
- Results (AP, 8 November): Senate at 54 Democrats (including two independents) to 44 Republicans, from 47 to 53 before the vote; House at 254 to 162, with 19 seats still uncalled (majority at 218).
- January agenda: repeal the tariffs, reverse the Medicaid cuts, vote on the war in Iran; Donald Trump promises a veto, which can only be overridden by two-thirds of each chamber.
- The budget, the real economic risk: federal funding expires on 11 December — the 2025 precedent was a 42-day shutdown; the debt ceiling ($41,100bn) is expected in 2027.
LUSIGNAN'S VIEW — The veto caps the legislative reach until 2029: for US yields, vigilance shifts to the budget deadlines. A rollback of tariffs would support European exporters, but no text is secured.
TECHNOLOGY & MARKETS
Nasdaq in correction: doubts about AI financing deepen
- Thursday 5 November: Wall Street's worst session since April 2025 — S&P 500 −4.4%, Nasdaq −5.5%, semiconductors −12%, around $3,000bn wiped out; Taiwan −4.5% the next day. Nasdaq nearly 12% below its record, partial rebound since.
- Regulatory trigger: 45% of planned US data-centre capacity sits in states likely to restrict it (Goldman Sachs); a moratorium promised by the governor-elect of Texas.
- Already fragile ground: over nine months, Microsoft, Alphabet, Amazon, Meta and Oracle invested $556.9bn against $542.9bn of operating cash flow; their free cash flow swings from +$143.5bn to −$14bn and share buybacks fall by 83%.
LUSIGNAN'S VIEW — The test runs through earnings releases: CoreWeave on Tuesday, Cisco and Applied Materials on Thursday, Nvidia on 17 November. Maintained 2027 budgets would argue for a breather; in portfolios, check the weight of semiconductors and diversify by earnings engines as well.
RATES & SOVEREIGN DEBT
US payrolls at +165,000, European inflation at 4%: December comes into focus
- United States: +165,000 jobs in October (65,000 expected), unemployment at 4.1%; a quarter-point adjustment on 9 December is 77% priced in (CME FedWatch).
- Europe: euro area flash inflation at 4.0%, the highest since 2023, driven by energy (+20.8%) — core stable at 2.5%; the Bank of England raises its rate to 4.00%, the first hike since 2023.
- France: 2027 budget rejected by the National Assembly (458 votes against); Senate from 20 November, S&P on the 27th; Bund-OAT spread back near 150 points, after 160 on 2 November.
LUSIGNAN'S VIEW — The surge in European inflation comes from the imported energy bill, not from underlying pressures. On Tuesday, the US monthly core reading (+0.2% expected) will set the tone for December.
ENERGY
Brent at $98: the market bets on a deal with Iran
- Oil: Brent at $98.32 on Friday, −16% over the week, the steepest fall since 2020; no deal signed, attacks on vessels persist near the Strait of Hormuz.
- Gas and power: TTF towards €85/MWh after a peak close to €104 at the end of October, European storage at 74%; French wholesale price at €278/MWh on 6 November.
- Majors: $62.6bn of combined adjusted net income in Q3 for seven groups (+145.5% year on year) despite an average Brent back from $104 to $97: refining takes over from upstream.
LUSIGNAN'S VIEW — A deal would bring European inflation back down in the spring and support the scenario of stable rates in 2027; a failure would send Brent back towards its recent highs. Among oil companies, the strength of the integrated model will be measured by the normalisation of refining margins.
OTHER NEWS
In brief
- European banks: Crédit Agricole proposes to merge its Italian subsidiary with Banco BPM (stake raised to around 45%); UniCredit posts a record quarterly profit of €3.3bn (+24%).
- Earnings: Air France-KLM: adjusted operating result +10% to €1.35bn, shares +12%; Palantir: revenue +96% to $2.31bn.
- Gold: central banks bought 321 tonnes in Q3, 63% of which was not officially reported (World Gold Council).
This is not investment advice.